M&A Market Update
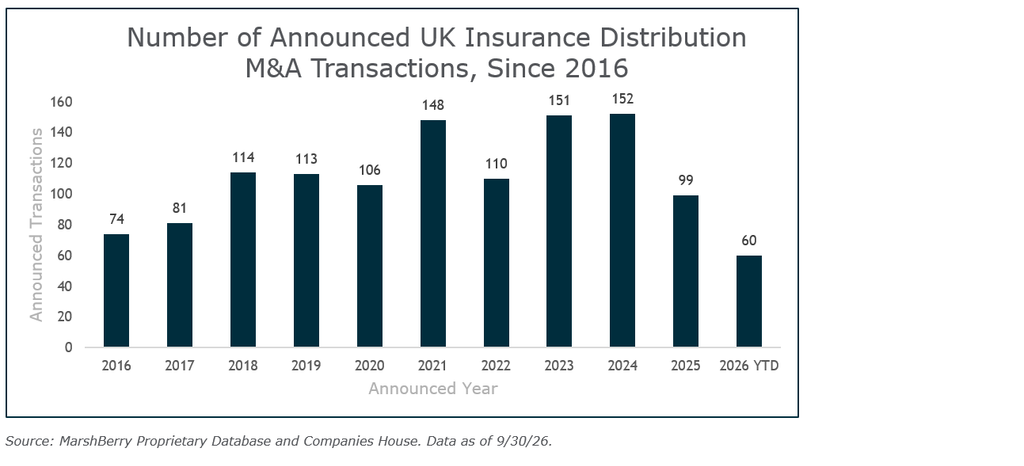
With only four new deals in September, on a year-to-date (YTD) basis there have been 60 announced merger and acquisition (M&A) transactions in UK insurance distribution, 22% lower than the 77 transactions announced at the same point last year. Q3 ended with a total of 18 announced deals, making it the quietist quarter for M&A by volume since Q2 2020, when Covid had applied a temporary handbrake to dealmaking.
While deal volumes remain muted in 2026, total M&A deal value is a different story. September saw (by far) the biggest deal of 2026 to date and the first £1bn+ sector deal since 2024. It was the third £100m+ sector deal in Q3 2026, taking the total for the year-to-date to five, the same number as in 2025. The total value of sector M&A in 2026 will be substantially higher than last year.
Deal volumes remain depressed, but large transactions are being completed
With only four new transactions to report on, the deal statistics for 2026 on a YTD basis have not changed a great deal since last month. Deal volumes have continued to track lower and will end the year with well under 100 announced deals – even if there is a flurry of activity later this month from private sellers that have been working hard to finalise transactions before 28 October, when the headline rate of Capital Gains Tax may be increased from its current level of 24%.
M&A deal values in 2026 tell a different story. In 2025 the total value of sector M&A was c.£2.1 billion. In 2026 there has already been more than £3 billion of deal value, with three months of the year still to go. Around half of that came in September with the largest deal of the year so far, EQT’s acquisition of a majority stake in McGill & Partners from Warburg Pincus, for a reported $2 billion. Deal value statistics are of course always skewed by the inclusion of one or two of the very large deals. There were few very big UK deals in 2025 and while the UK cannot expect to see the sort of ‘mega deals’ that have become more common in the U.S. recently, this year has seen a number of very sizeable transactions take place.
Private equity continues to drive activity at the top end of the market
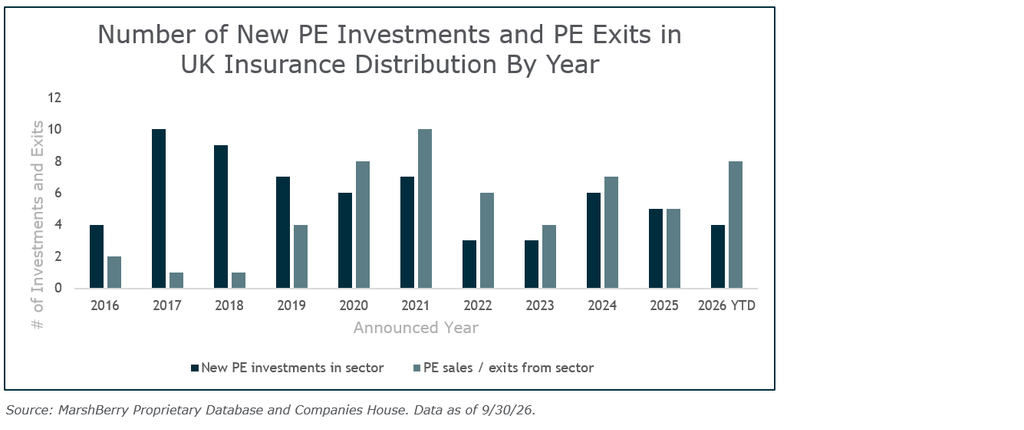
This increase in deal values is being driven by private equity (PE). Of the 60 deals in 2026 so far, eight have involved sales by PE. There were only five PE exits in 2025 and you have to go back to 2021 (when there were ten) to find as many exits as we have already seen this year. PE deals naturally involve much larger average targets than private deals. The five largest UK deals of the year have all been PE exits. However, three of these (McGill & Partners, Optio Group and Prestige) have also involved a PE buyer (i.e., secondary deals). These are refinancing transactions, with one financial investor replacing another – not industry consolidation.
At the end of the year MarshBerry will crunch the numbers to consider M&A volumes and values both including and excluding such transactions, to show how far sector M&A statistics are reflecting consolidation, and how much is just refinancing.
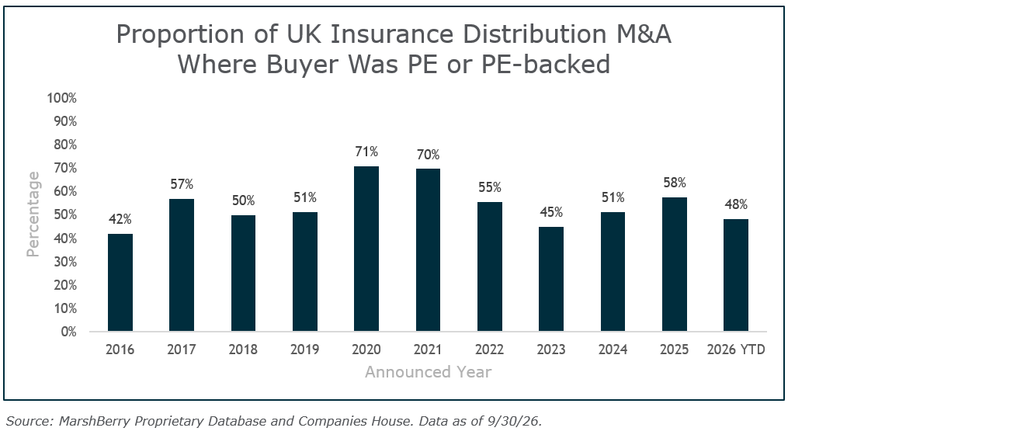
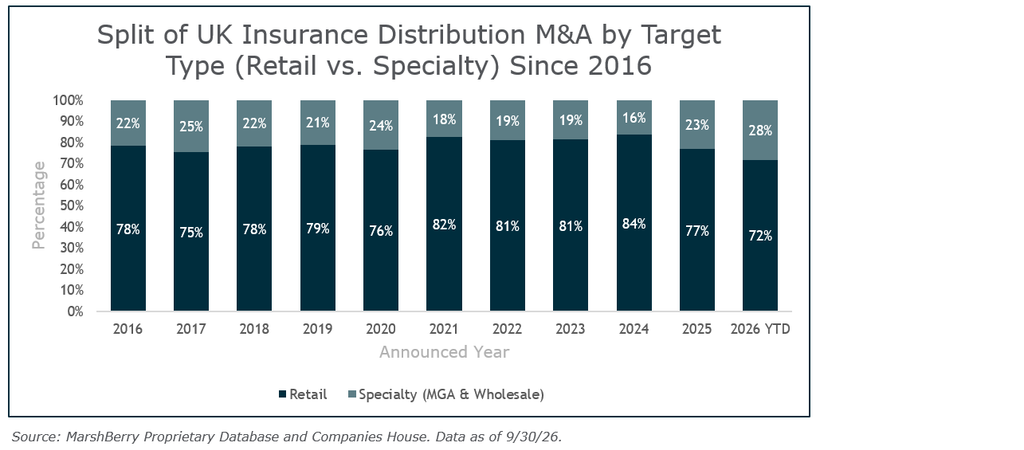
What EQT’s investment in McGill & Partners does demonstrate is that PE has not lost its enthusiasm for investment into the sector. PE and PE-backed buyers have accounted for just under half (48%) of all deals in 2026. It also shows that specialty business is now attracting PE capital more readily and in higher volumes than retail broking, where the opportunity for rapid growth (both organic and inorganic) is typically lower. McGill’s secondary deal in September follows similar refinancing transactions by Optio Group in July and Carbon Underwriting in June. Specialty targets have accounted for 28% of M&A by volume in 2026, but more than 85% of all deal value. In addition to PE buyers, specialty targets have also continued to attract strong interest from overseas buyers, with acquirers from the U.S., Japan and Australia all having completed sizeable specialty transactions in 2026.
As noted above, this month we have a new Budget from a new Chancellor and Prime Minister. A number of sellers are working hard to complete transactions before the 28th October. We therefore expect to have more than just four deals to report on in next month’s Viewpoint.
Notable transactions (September 2026):
- As noted above, in the largest sector deal for more than two years, Swedish private equity investor EQT announced a $2 billion deal for McGill & Partners, the London-based global specialty broker formed by Steve McGill and backed by Warburg Pincus since 2019.
- Brown & Brown (Europe) announced that it has acquired Alan R. MacKay & Co (t/a MacKay Corporate Insurance Brokers), a leading chartered broker operating across three offices in Scotland. The transaction is Brown & Brown’s first retail acquisition in Scotland and will form a base for further expansion across the country. MarshBerry advised MacKay Corporate on the transaction.
- Tower Insurance Brokers, a commercial broker in Lytham, announced it has completed its first acquisition since raising finance from private credit investor TDC, acquiring Riskworks in Cheshire. Tower has stated that it is considering further deals and has plans to grow into a £100m GWP business.
Other transactions (September 2026)
- Jensten Group announced the acquisition of Venture Risks Group (VRG), a technology-focused commercial broker.